
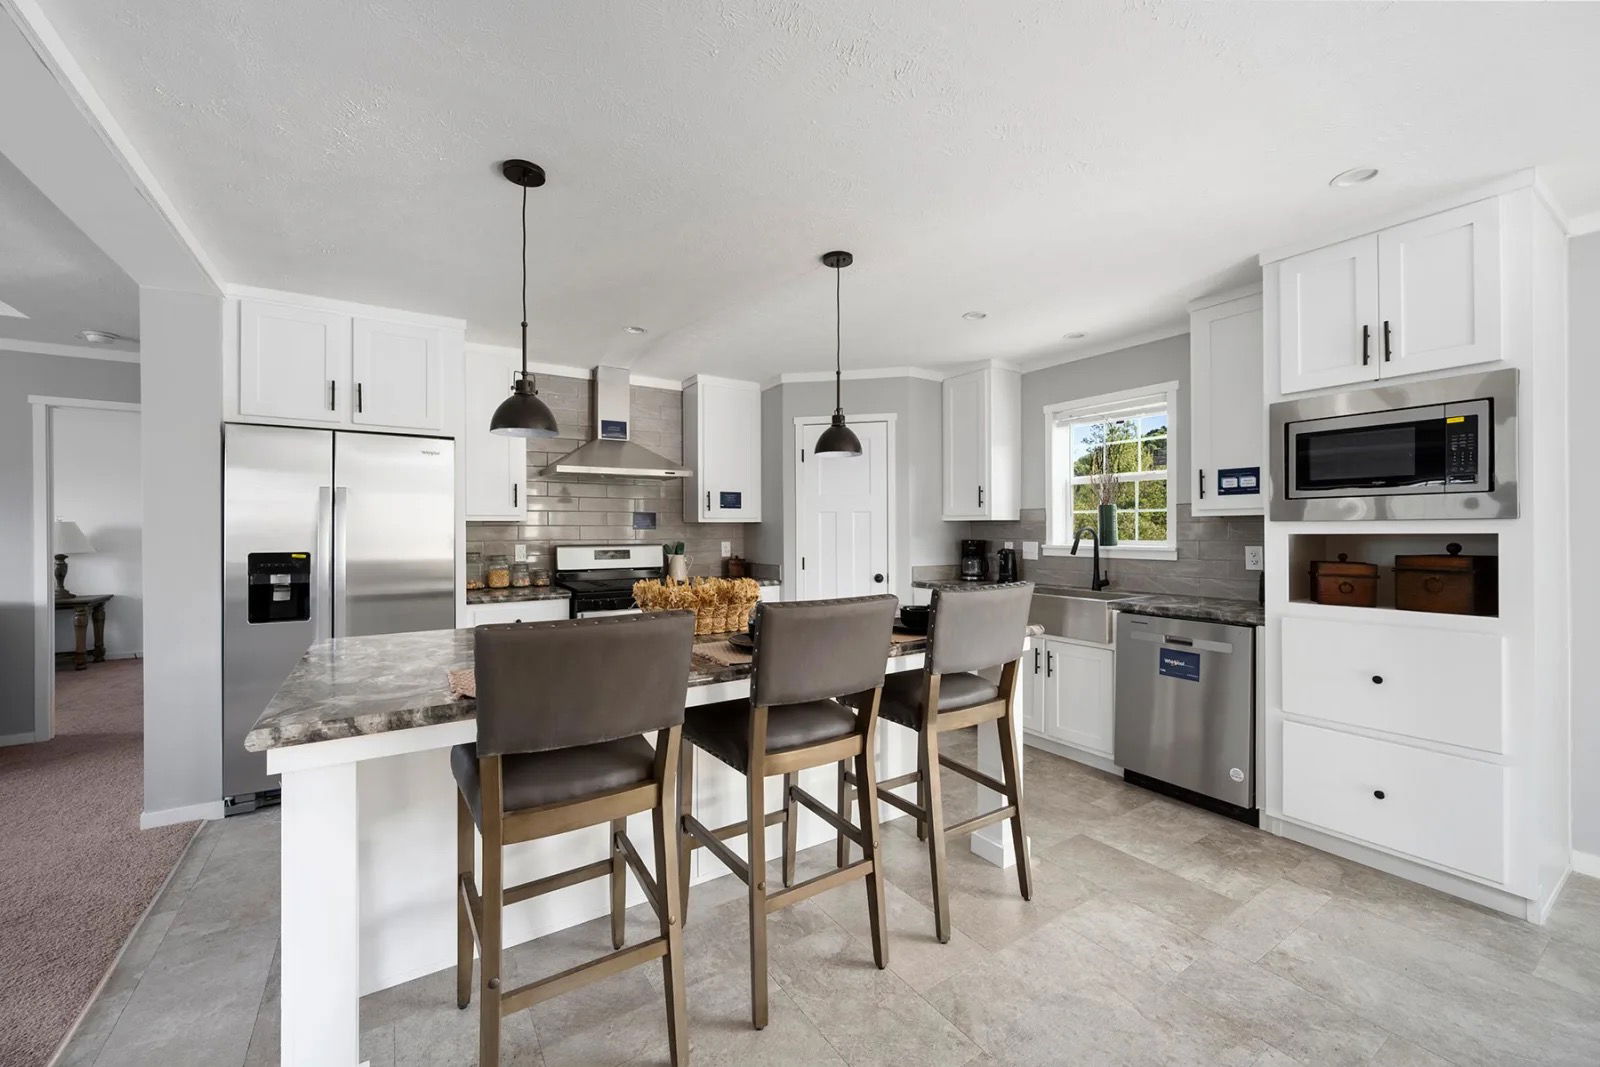
Lewiston, ME Buyers: Budgeting a Manufactured Home Loan
Planning a manufactured home in Lewiston or Androscoggin County, ME? Start from a real listed price, then match it to a loan path that fits your land.
11/18/2026
If you live in Lewiston, Auburn or anywhere else in Androscoggin County, Maine, and you're thinking about a new manufactured home, the financing question usually comes first: "What can I actually afford, and what kind of loan fits?" This guide walks through a practical, price-first way to plan it, using real listed prices from Northern Mobile Homes in Rochester, NH, and the official rules from HUD and MaineHousing. No rate quotes here (those change and depend on you), just the steps that help you walk into a lender's office prepared.
Step 1: Start with a real price, not a guess
A lot of buyers start by asking about loans in general. It's easier to start with an actual home and price, then work backward. Northern Mobile Homes lists prices on its catalog, and several homes are marked as Special Offers right now. A few examples from the current listings:
- Onyx 40 (Clayton Gem): 1 bed, 1 bath, 527 sq ft, listed at $62,900
- Topaz (Clayton Gem), Special Offer: 3 beds, 2 baths, 869 sq ft, $79,900
- Franklin (Independence series), Special Offer: 3 beds, 2 baths, 1,280 sq ft, was $97,900, now $85,250
- Hancock (Independence series), Special Offer: 4 beds, 2 baths, 1,440 sq ft, was $102,900, now $89,250
Pick one or two that fit your household, then write down that price. That number is the starting point for every lender conversation. Keep in mind that your total project may include more than the home itself. Land, site preparation, a foundation, utility hookups and delivery can all add to the budget, so ask the office what a listed price covers for your situation before you settle on a loan amount.
Step 2: Decide where the home will sit
The single biggest factor in which loan fits is the land. In Androscoggin County, buyers usually fall into one of three situations:
You already own land. If the home will sit on your own lot, you may be able to finance the home and land together, or just the home. Loans that treat the home as real estate generally require it to be permanently attached to a foundation that meets state and local rules.
You're buying land too. Some programs can cover both the lot and the home in one loan. This takes more planning (surveys, septic or sewer, a well or water hookup), so allow extra time.
You're placing the home on leased land. Some loan programs allow leased lots, but they usually set lease requirements, so have your lease terms handy.
Step 3: Know the main loan paths
Here's what the official sources say about two options Maine buyers often ask about. Your lender will tell you which you actually qualify for.
FHA Title I manufactured home loans. According to HUD's Title I page, FHA-approved lenders make these loans to buy a manufactured home, a lot, or both. HUD says the buyer must intend to live in the home as their principal residence and meet FHA credit standards. The home must be installed on a foundation that follows state and local rules, and the site needs adequate water and sewage disposal. If the lot is leased, HUD sets an initial lease term of three years with at least 180 days' written notice before termination. HUD also notes that a dealer or retailer can help point you to local lenders who finance manufactured homes.
MaineHousing First Home Loan. MaineHousing's First Home Loan page says the program is offered only through its participating lenders. It counts you as a first-time buyer if you haven't owned your principal home in the past three years, and it lists a 640 minimum credit score. MaineHousing says eligible homes include permanently attached mobile homes built within the last 20 years, on owned or leased land, and it describes a separate option for single- and double-wide homes with a $200,000 statewide purchase price limit. Income and price limits apply, so check the current figures with MaineHousing or a participating lender before you count on it.
Other common routes, such as conventional mortgages or home-only loans, depend on the lender, so ask about them when you apply.
Step 4: Get your paperwork ready
Lenders will want to see your income, your debts and your credit. Pulling together recent pay stubs, tax returns and bank statements before you apply speeds things up. If you plan to use land you own, have the deed and any survey on hand. If you're leasing, bring the lease.
How Northern Mobile Homes can help
On its financing page, Northern Mobile Homes says it works with lenders who specialize in mobile home loans and will guide you through the application and help you understand your options. When you're ready, you can start the credit application online. It's a good idea to ask the team directly about delivery and setup for an Androscoggin County site, and which loan paths fit the home you've chosen.
Ready to run the numbers?
Browse every model and current Special Offer on the Northern Mobile Homes homes page, then visit the lot at 176 Farmington Rd, Rochester, NH 03867, or call (603) 330-5000. Prefer to start online? Send a note through the contact page and tell them the home you're looking at and where in Androscoggin County you plan to place it.

Northern Mobile Homes
Northern Mobile Homes stands out as New Hampshire’s best option for manufactured homes, thanks to our unbeatable combination of exceptional service, affordable prices, and a vast selection. Visit us today to experience why local homebuyers consistently choose New England Mobile & Manufactured Homes as their trusted home dealer. New England Mobile & Manufactured Homes is the best choice for your manufactured or mobile home in Rochester, NH.
Get started with Northern Mobile Homes
Find, design, and order your next home in a few clicks.
Dealer License #:


